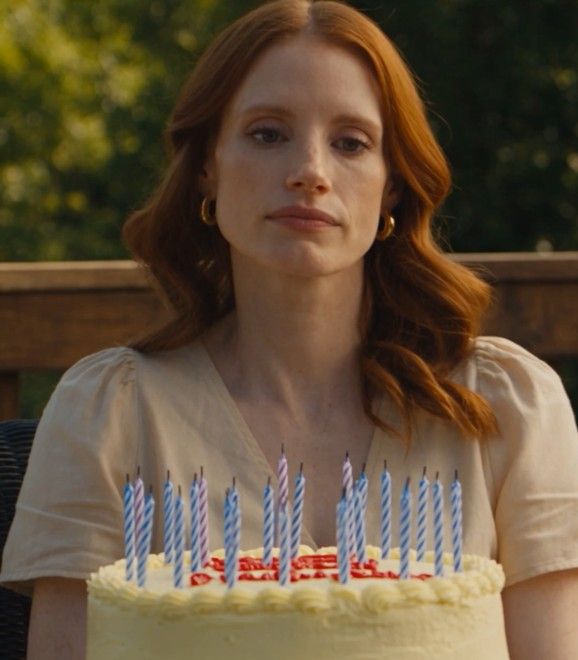
Sloan’s elbow moved before the lemon cake fell. I watched Brenda’s homemade birthday gift slide off the table and break against the patio stones, scattering sixty-five candles between our guests’ shoes.
“Oops,” my daughter-in-law said.
My son Harrison stood beside the grill. At thirty-five, he was old enough to understand what had happened. He looked at the ground instead.
I walked to the fire pit, lifted the Gucci handbag Sloan had displayed all afternoon, and placed it in the glowing embers. Smoke curled from the leather.
“Mom!” Harrison shouted. “What are you doing?”
I met his eyes. “Oops.”
The silence afterward frightened me more than the shouting. I had done something I could not undo, and for the first time in a year, nobody could pretend our arrangement was working.
Harrison and Sloan had moved into my house temporarily. Twelve months later, Sloan’s clothes filled my drawers, her toiletries occupied my bathrooms, and her opinions governed my kitchen. When I complained, Harrison always offered the same explanation.
“She’s stressed, Mom.”
Then the same instruction.
“Stop making everything a fight.”
I had stopped. I made smaller meals, used another bathroom, and waited until they left before sitting in my favorite chair. Peace had become something I bought by making myself inconveniently small.
The morning after my birthday, Harrison demanded an apology and $2,500 for the purse.
“No,” I said.
He stared as though I had forgotten which of us owned the house. Sloan stood behind him, arms folded, waiting for me to become reasonable again.
Instead, I boxed belongings she had spread through my private rooms, put locks on those doors, and stopped supplying groceries for two adults who treated my kindness as a permanent service.
I knew boundaries would not repair the handbag. I also knew paying for it that morning would let them turn the ruined cake into something nobody mentioned again.
At the bank, I asked about the emergency account Harrison had access to. I expected a balance and perhaps a few ordinary withdrawals. The representative printed statements and placed them carefully in front of me.
Designer stores. Restaurants. Spa visits. Boutique purchases.
Nearly $18,000 had disappeared.
I traced one charge with my finger. It fell on the week Harrison told me he could not contribute toward utilities. Another came two days after Sloan said she had bought her handbag with money from her family.
The following afternoon, Harrison called. I sat at my table with the statements spread beneath the kitchen light and answered before he could rehearse an excuse.
“Tell me exactly what Sloan has done.”
For several seconds, I heard nothing but his breathing. Then my son whispered something that made the missing money feel suddenly smaller. I pulled the statement closer, and he asked whether I had checked the envelope Sloan left beside my birthday cards.
I reached for the envelope without putting down the phone. It was cream colored, expensive, and still sealed. I had assumed it contained a birthday card from someone who could not attend.
“What’s inside?” I asked.
“An application,” Harrison said. “For a home equity loan.”
The flap tore beneath my thumb. I drew out several folded pages and saw my address, my name, and a signature that looked enough like mine to make my skin turn cold.
“I didn’t sign this.”
“I know.”
The admission was so quiet that I almost missed it. Harrison had found an email on the computer they shared. Sloan had arranged preliminary paperwork using information kept in my filing cabinet. The copy in the envelope was supposed to become something he could persuade me to approve after my birthday.
“Has any loan been funded?” I asked.
“I don’t think so.”
“Don’t guess.”
He promised to send the correspondence. I told him to preserve the originals and stop discussing my financial information with anyone. Then I ended the call and sat still until I could trust my hands to dial the number printed on the application.
The lender would not disclose everything immediately. There were verification steps, and I followed them. Eventually a representative confirmed that an inquiry and incomplete application existed, but no loan had closed. I stated clearly that I had not authorized it and asked how to document that objection.
She explained the next steps without promising that one telephone call would solve them all. I wrote them down. Relief arrived as a small, hard thing: my home had not been pledged, but somebody had tried to make it available.
Brenda came over when I called her. She entered through the back door carrying a container of soup and looked first at the table, then at me.
“I can’t believe I burned that bag,” I said.
“I can believe you reached your limit,” she answered. “That doesn’t make burning it right.”
