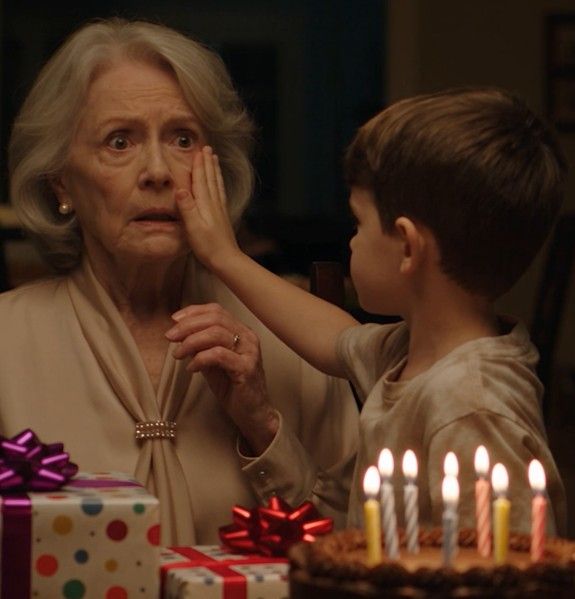
My ten-year-old grandson slapped me in the face at his birthday dinner, and my son laughed before reminding me that the boy’s private-school tuition was due the next morning.
The room smelled of roast chicken and birthday candles. Liam stood beside my chair with his hand suspended in the air. Across the table, my daughter-in-law, Emily, folded her arms.
“Go on,” she said. “Hit him back if you dare.”
Daniel grinned. The same child I once taught to apologize for stepping on someone’s foot now seemed delighted that his own son had struck his grandmother.
“Why?” I asked Liam.
He shrugged. “Dad says you’re always bossing everybody around.”
My cheek burned. I had come carrying a wrapped book, a birthday card, and the quiet hope that dinner might feel like family again. Instead I watched Liam deliberately push my water glass off the table. It shattered across the hardwood.
Nobody corrected him.
“Kids need freedom,” Daniel said.
“Kids need parents,” I answered.
I left before dessert. Daniel followed me to the door, and for one foolish second I hoped he would apologize. He merely called, “Westbrook tuition comes out tomorrow. Don’t forget.”
For three years, after his commercial printing business failed, I had paid the $3,280 mortgage on their four-bedroom house. Then came tuition, taxes, insurance, repairs, and the small cash transfers that never stayed small.
My late husband, Robert, had believed that love without boundaries could become another kind of harm. I once argued with him about that. That night, I finally understood.
At home I opened my laptop and canceled the scheduled Westbrook Academy payment. I canceled the mortgage transfer and the other voluntary payments. Then I called our financial adviser, Thomas Reid, and asked him to suspend everything supporting Daniel’s household.
The next morning Daniel called, furious. When I explained that I had chosen to stop funding their lifestyle, he accused me of punishing a child.
“No,” I said. “I’m asking his parents to act like parents.”
Thomas sent me thirty-six months of transactions. As the printer hummed, Daniel demanded to know what I was doing.
“Finding out exactly what this has cost me,” I replied.
Then my eyes settled on a line Thomas had highlighted in yellow. It wasn’t the tuition or mortgage. It was a transfer to an account I had never heard of, approved from an email address that appeared to be mine.
I called Thomas back immediately. “Did I authorize this?”
His voice changed. “That’s what I needed to ask you.”
The transfer was marked as family support. Its recipient was not the school, the bank, or any household service. And next to the unfamiliar account was a name I recognized with a shock: Daniel Ellis.
My son was still shouting through the other phone when Thomas said, “There are more of these. Mrs. Ellis, how long has your son had access to your email?”
I put Daniel on hold without saying goodbye. Thomas waited while I found the note where I kept old passwords, a yellow index card tucked inside Robert’s gardening book. The address printed beside the highlighted transfer was similar to mine, but the letter between my first and last name had been changed. For years I had assumed messages bearing my signature came from my own account. Now a stranger’s version of my name had been used to move money that was supposed to support a family. I asked Thomas to read the transaction dates aloud.
There were four transfers, not one. Each went to an account whose beneficiary was listed as Daniel Ellis, and each authorization was attached to an email that looked as though I had sent it. The amounts were smaller than the mortgage payments, irregular enough to hide among the dozens of reimbursements I had approved willingly. Thomas made a distinction I needed to hear. “The household support you authorized is one thing,” he said. “These transfers may be something else. We need the bank’s records before reaching conclusions.” I wrote every date down.
My hands had begun shaking. I was angry with Daniel for what he had said, angry with myself for not looking closer, and frightened that I could no longer tell which transactions were gifts and which had been taken from me. Thomas asked whether I had ever shared my email password. Years before, when Robert was alive and I struggled with a printer installation, Daniel had configured my computer. I had told him the password while he sat beside me. I never changed it because there never seemed to be a reason.
I ended Daniel’s call and sent him a brief message saying I would communicate in writing after reviewing my finances. Within a minute he called again. Then again. He finally sent a text accusing me of being vindictive, followed by a photograph of Liam looking miserable at breakfast. That image almost undid me. The boy in the photograph was ten, not a villain. But I reminded myself that giving his parents unchecked access to my accounts had not taught him kindness. It had merely hidden the price of their choices.
Thomas explained that we should contact the bank’s fraud department promptly, secure my email, and preserve the messages before making accusations. I called from my own phone while he stayed on the line as an adviser, not as someone with the power to reverse transactions. A representative opened a case, documented the disputed authorizations, and explained that recovery depended on the evidence, the account terms, and the bank’s investigation. We changed access credentials, enabled multifactor authentication, and reviewed every standing transfer. It took hours. No money magically returned to my account.
When the calls were finished, I made tea and stared at Robert’s empty chair. He had once spent an entire summer teaching Daniel to replace a damaged headlight after the boy borrowed our car without permission. Robert did not refuse to help; he stood beside him, handing over tools and insisting he do the work. I had accused Robert of making a simple mistake into a moral lesson. “Responsibility is not punishment,” he’d told me then. I wished he were there to say it again, although he probably would have been gentle enough not to remind me he had been right.
The next day I went through the records with a pencil. Thirty-six months of mortgage payments at $3,280 each was already more than a hundred thousand dollars. Tuition, property taxes, insurance, and repairs added far more. I did not calculate the total to create a bill I could force my son to pay. Most of the transfers had been freely given without a written repayment agreement. I calculated it because the blur of family duty had made me forget that the money represented my own years of work, my own retirement, and Robert’s careful savings.
